fact_checkResearch-based first look
Table of ContentsOpenClose
- Forml at a glance
- What Forml is designed to do
- The part I like most
- Core features and buyer value
- The catch
- Forml pricing in 2026
- Who should use Forml?
- How I would test Forml
- Forml alternatives
- Related reading for this decision
- My final verdict
- Frequently asked questions
| Question | Answer |
|---|
| What is it? | agentic AI lending operations platform |
| Best for | lenders exploring automation for document-heavy operational workflows with strong compliance, model-risk and review capabilities |
| Less suitable for | buyers seeking a self-serve SaaS product or any lender unwilling to run formal fair-lending and decision-governance validation |
| Pricing | Sales-led unless stated otherwise below |
| Review access | Public-evidence first look; no authenticated workspace |
| Main buying test | Prove accurate, governed outcomes on representative work |
The product is designed around five buyer jobs:
- Read documents and internal or external data sources
- Extract structured lending information
- Insert knowledge into existing operational processes
- Support or automate defined decisions
- Execute follow-on actions within lending workflows
The part I like most
I can see value in reducing document handling before a credit decision is made.
- Addresses document and workflow friction in lending
- Combines extraction with process action rather than stopping at OCR
- A focused vertical may support deeper domain design
- Could shorten manual processing if evidence proves reliable
Core features and buyer value
Document and data ingestion
Forml publicly describes reading from varied documents and sources. Test OCR, handwriting, tables, conflicting values and provenance, with every extracted field linked to the original page.
Process integration
Value depends on fitting established origination and servicing systems. Confirm APIs, supported systems, idempotency, exception queues and what happens when a source changes.
Decision support
Automated lending decisions are consequential. Separate eligibility rules, model scores and generated reasoning, and require an adverse-action and appeal process where applicable.
Agentic actions
Execution can remove manual work but raises the cost of errors. Begin with drafts and suggestions, then permit only reversible low-risk actions after evidence.
Evidence maturity
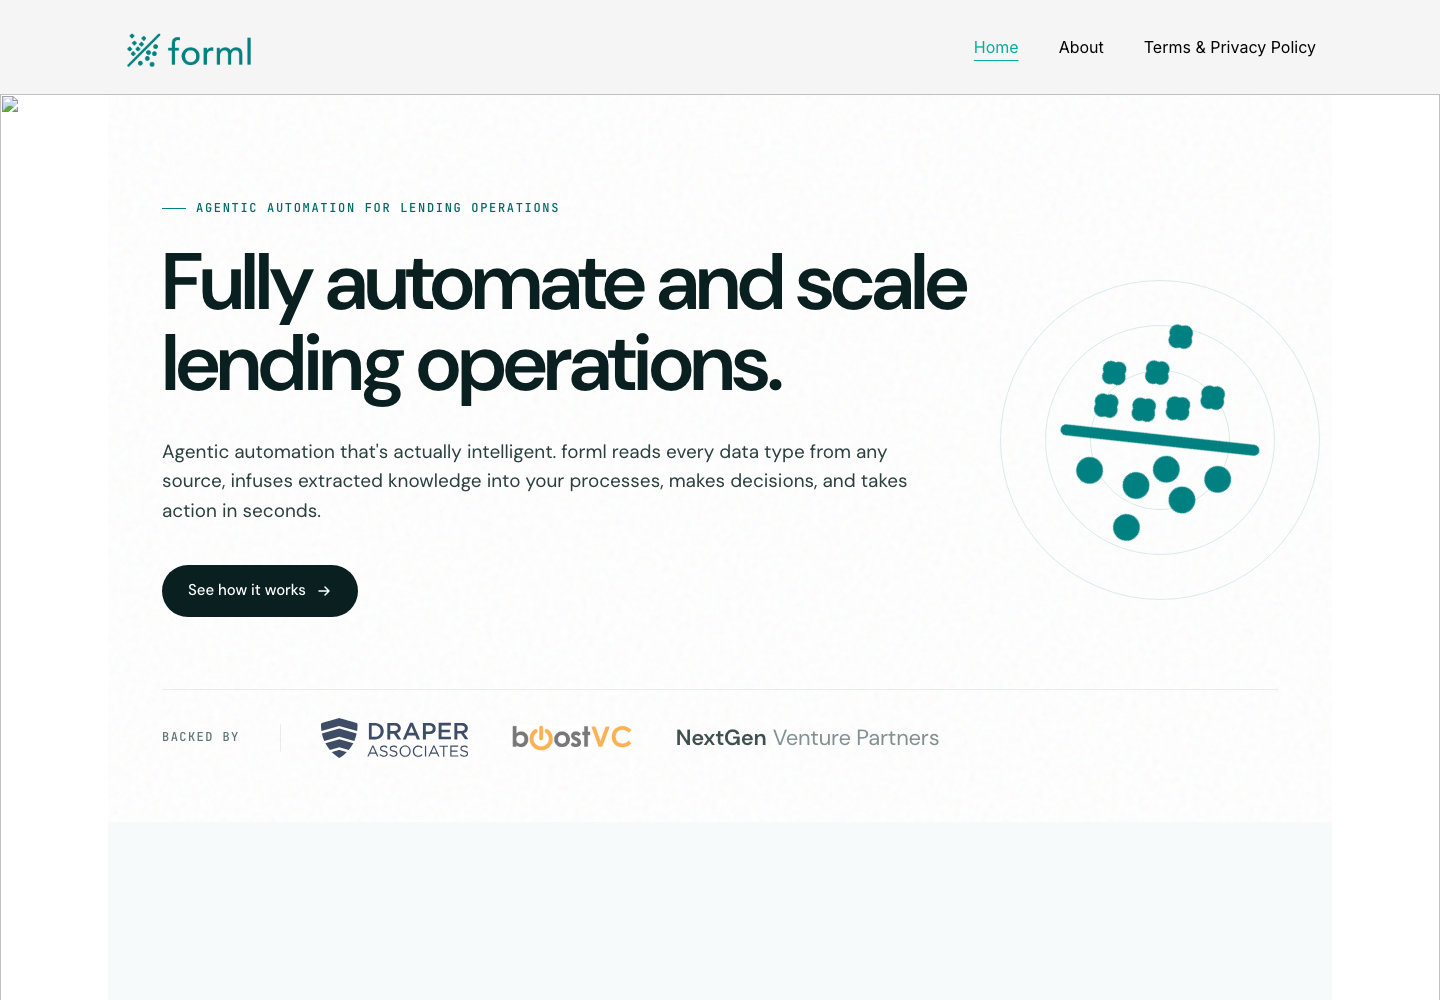
The official site currently offers limited readable product detail. Investor and company descriptions help identify positioning but cannot replace product documentation or testing.
The catch
I would keep credit decisions with authorised human reviewers until extraction errors, model risk and fair-lending concerns have been independently assessed.
- Very limited public product and pricing documentation
- Lending decisions carry serious regulatory and fairness risk
- Agentic actions could propagate extraction mistakes
- Integration and customer evidence require verification
Pricing evidence was recorded on 20 July 2026. The figures and plan descriptions below are historical research, not a newly verified quote. Confirm current terms with Forml before budgeting.
Forml does not publish a complete public rate card. Request pricing by application, document, workflow, action, environment and implementation. Commercial discussion should follow—not precede—documentation of supported use cases, model governance, audit evidence and regulatory responsibilities.
Forml is best suited to lenders exploring automation for document-heavy operational workflows with strong compliance, model-risk and review capabilities.
It is less suitable for buyers seeking a self-serve SaaS product or any lender unwilling to run formal fair-lending and decision-governance validation.
For Forml, my proposed test would use this scenario rather than begin with a production rollout:
A lender supplies a blinded set of applications and supporting documents with human-labelled fields and outcomes. Forml extracts data and proposes next steps without acting. Reviewers measure field accuracy, disparate impact, override reasons and evidence completeness before connecting a sandbox system.
| Alternative | Consider it when |
|---|
| Ocrolus | Document automation and cash-flow analysis are the primary need |
| Amount | Digital lending origination and decisioning infrastructure dominate |
| Alloy | Identity and fraud orchestration lead |
| nCino | A mature bank operating platform is required |
| Manual reviewed automation | Human accountability must remain central |
Before adding Forml to a shortlist, I would write down the job, the current alternative and the evidence needed to justify a change. Our guide to a requirements-first approach to choosing AI tools.
For Forml, I would also count the existing tools, review time and operating work that remain after adoption. Our guide to a framework for reviewing overlapping software costs.
I would use the AI Tool Chooser to organise the shortlist around requirements before a vendor discussion. It does not replace the product-specific, technical or professional validation described for Forml.
For related finance buying decisions, I would also read our AlphaSense review and Astrada review. These are adjacent evaluations, not a claim that every product replaces Forml.
My final verdict
I would put Forml on a conditional shortlist for lenders exploring automation for document-heavy operational workflows with strong compliance, model-risk and review capabilities.
I would keep credit decisions with authorised human reviewers until extraction errors, model risk and fair-lending concerns have been independently assessed.
Frequently asked questions
Forml describes an agentic AI platform for automating and scaling lending operations.
No complete public pricing table was available.
No. Public product evidence was limited, so this is explicitly an evidence-limited first look.
No. It is a research-based first look using official public evidence. No authenticated workspace or production integration was tested.
No commercial relationship was disclosed for this review, and no rating was assigned.
Tolu S.
Operations Lead, AI Search & GEO
Leads operations for AI search visibility and generative engine optimization (GEO) campaigns.