fact_checkResearch-based first look
Table of ContentsOpenClose
- Astrada at a glance
- What Astrada is designed to do
- The part I like most
- Core features and buyer value
- The catch
- Astrada pricing in 2026
- Who should use Astrada?
- How I would test Astrada
- Astrada alternatives
- Related reading for this decision
- My final verdict
- Frequently asked questions
Astrada at a glance
| Question | Answer |
|---|
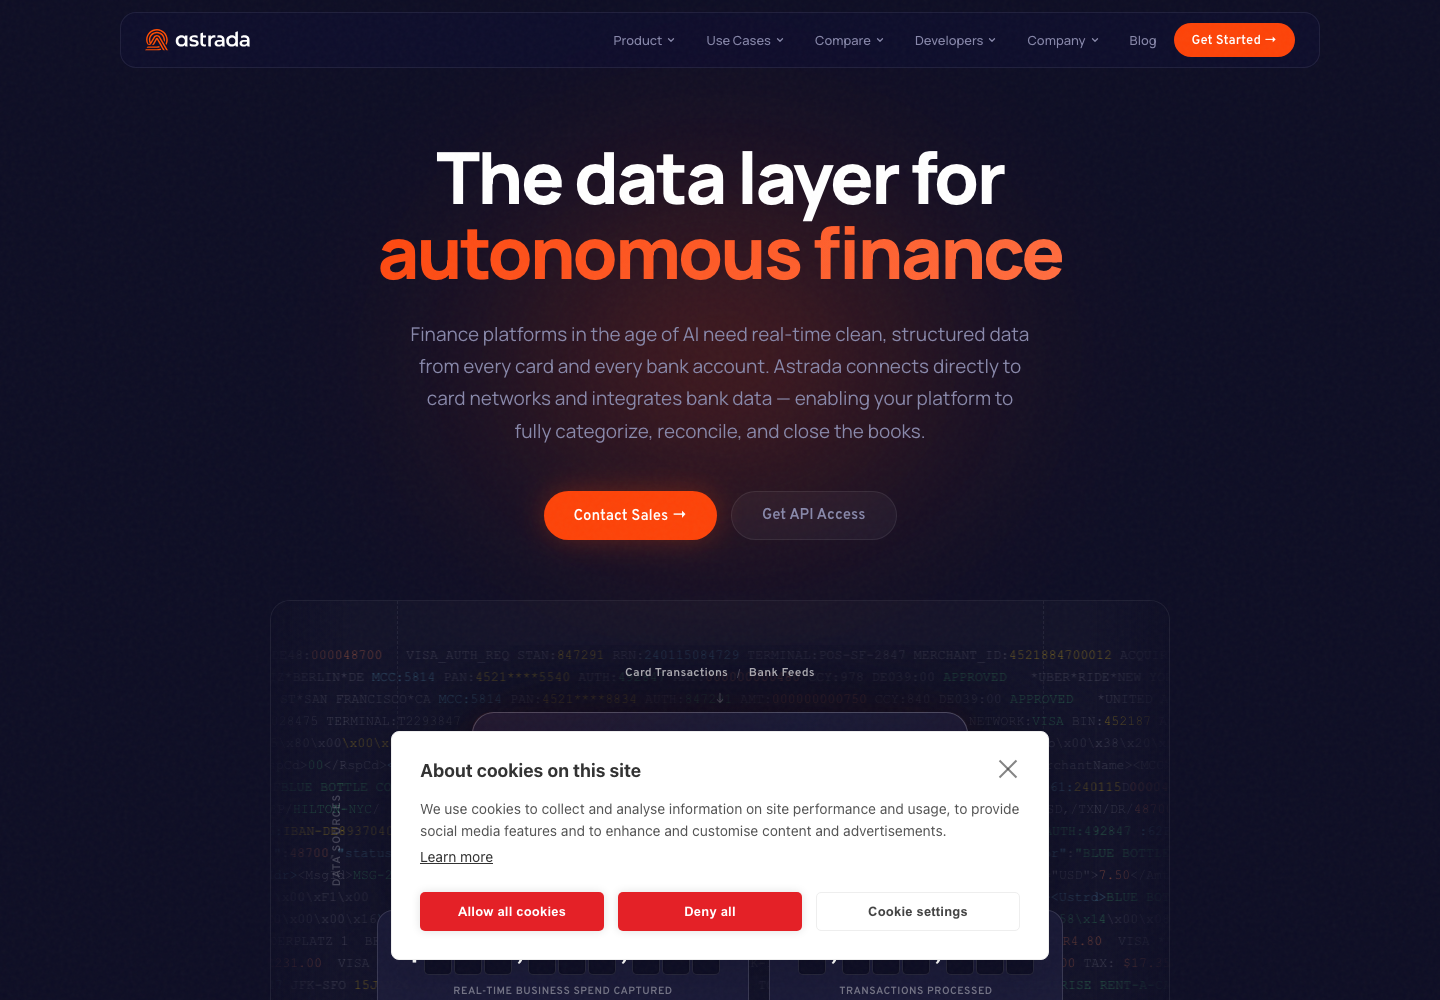
| What is it? | real-time card transaction data infrastructure for finance platforms |
| Best for | finance software platforms needing real-time structured transaction data from users’ existing personal or corporate cards |
| Less suitable for | end businesses seeking a standalone expense app or platforms operating mainly with unsupported debit, prepaid or closed-loop cards |
| Pricing | Sales-led unless stated otherwise below |
| Review access | Public-evidence first look; no authenticated workspace |
| Main buying test | Prove accurate, governed outcomes on representative work |
What Astrada is designed to do
The product is designed around five buyer jobs:
- Enroll supported cards without issuing a new card programme
- Receive structured transactions at authorisation time
- Add card-network fields beyond bank-feed merchant strings
- Match card events with bank statements automatically
- Power real-time policy, categorisation and finance agents
The part I like most
Authorisation-time card data is interesting because a finance workflow can respond before a delayed statement arrives.
- Can add visibility without forcing a platform-issued card
- Network data is richer and faster than conventional bank feeds
- Supports real-time policy and agent use cases
- Developer documentation publishes important coverage boundaries
Core features and buyer value
Bring Your Own Card
Astrada allows enrolled cards from existing issuers to feed a finance platform. User enrolment friction and issuer coverage determine whether the theoretical visibility gap actually closes.
Direct network data
Visa, Mastercard and selected American Express data can arrive with richer fields and lower latency than bank feeds. Validate reversals, tips, offline transactions, FX and incremental authorisations.
Live Transaction Data API
The API is the integration surface for finance platforms. Test webhook signing, ordering, duplication, retries, sandbox fidelity and stable identifiers.
Auto-reconciliation
Structured fields may improve card-to-bank matching. Measure precision, unmatched cases and false matches across real statement formats and multi-currency activity.
Coverage and compliance
Public docs list supported card types and regions. PCI scope, consent, retention and end-user disclosures must be mapped into the customer platform.
The catch
An authorisation is not a settled expense; reversals, duplicates and unsupported cards can undermine the apparent completeness.
- Coverage excludes several card categories
- User enrolment and consent can constrain adoption
- Pricing is not publicly standardised
- Real-time and settled transactions require careful lifecycle logic
Astrada pricing in 2026
Pricing evidence was recorded on 20 July 2026. The figures and plan descriptions below are historical research, not a newly verified quote. Confirm current terms with Astrada before budgeting.
Astrada does not publish a complete standard rate card. Ask whether pricing is based on enrolled cards, active cards, authorisations, transactions, API calls or matched statements. Include minimums, network regions, sandbox, implementation and support.
Who should use Astrada?
Astrada is best suited to finance software platforms needing real-time structured transaction data from users’ existing personal or corporate cards.
It is less suitable for end businesses seeking a standalone expense app or platforms operating mainly with unsupported debit, prepaid or closed-loop cards.
How I would test Astrada
For Astrada, my proposed test would use this scenario rather than begin with a production rollout:
A travel platform invites a user to enrol an existing commercial card. Astrada sends an authorisation event with structured fields, the platform applies policy immediately and later matches the settled transaction to a statement. Tests cover reversals, duplicates, FX and unenrolled virtual child cards.
Astrada alternatives
| Alternative | Consider it when |
|---|
| Fidel API | Card-linking and transaction APIs are the closest comparison |
| Plaid | Bank-account connectivity is more important than card-network events |
| Lithic | The platform wants to issue and control its own cards |
| Marqeta | Modern card issuing and processing are required |
| Teller | Direct bank connectivity for supported US institutions is the priority |
Before adding Astrada to a shortlist, I would write down the job, the current alternative and the evidence needed to justify a change. Our guide to a requirements-first approach to choosing AI tools.
For Astrada, I would also count the existing tools, review time and operating work that remain after adoption. Our guide to a framework for reviewing overlapping software costs.
I would use the AI Tool Chooser to organise the shortlist around requirements before a vendor discussion. It does not replace the product-specific, technical or professional validation described for Astrada.
For related finance buying decisions, I would also read our AlphaSense review and Caruso review. These are adjacent evaluations, not a claim that every product replaces Astrada.
My final verdict
I would put Astrada on a conditional shortlist for finance software platforms needing real-time structured transaction data from users’ existing personal or corporate cards.
An authorisation is not a settled expense; reversals, duplicates and unsupported cards can undermine the apparent completeness.
Frequently asked questions
What is Astrada?
Astrada provides real-time structured card transaction data APIs for finance platforms.
Does Astrada issue cards?
Its core proposition is bring your own card, allowing supported existing cards to be enrolled.
Which cards are supported?
Public docs list selected Visa, Mastercard and American Express credit or commercial debit products across specified regions.
Was this Astrada review hands-on?
No. It is a research-based first look using official public evidence. No authenticated workspace or production integration was tested.
Did Astrada pay for inclusion?
No commercial relationship was disclosed for this review, and no rating was assigned.
Tolu S.
Operations Lead, AI Search & GEO
Leads operations for AI search visibility and generative engine optimization (GEO) campaigns.